Fund Reserve, outperform your savings account.
Reserve is a balance that rewards you through the card, the bills, and the bitcoin buys you'd make anyway. Paid in bitcoin, not interest.
- Up to 5%* back on card spend
- Up to 3% back on bill pay
- Zero-fee bitcoin trading
- No Fold withdrawal fee
- 3% commitment bonus
Fold Reserve is closed-loop stored value, not a deposit account, and is not FDIC insured. Your Reserve balance sets your reward rate but earns nothing itself. Rewards require a $5,000 balance, and the 5% rate requires the Fold Bitcoin Credit Card, a $100,000 balance, and applies to the first $5,000 of eligible purchases each calendar month. The 3% bonus is a one time amount applied to your commitment and paid in three annual installments, is not an annual rate, and is forfeited if your balance falls below your commitment. Fold's terms and conditions apply.
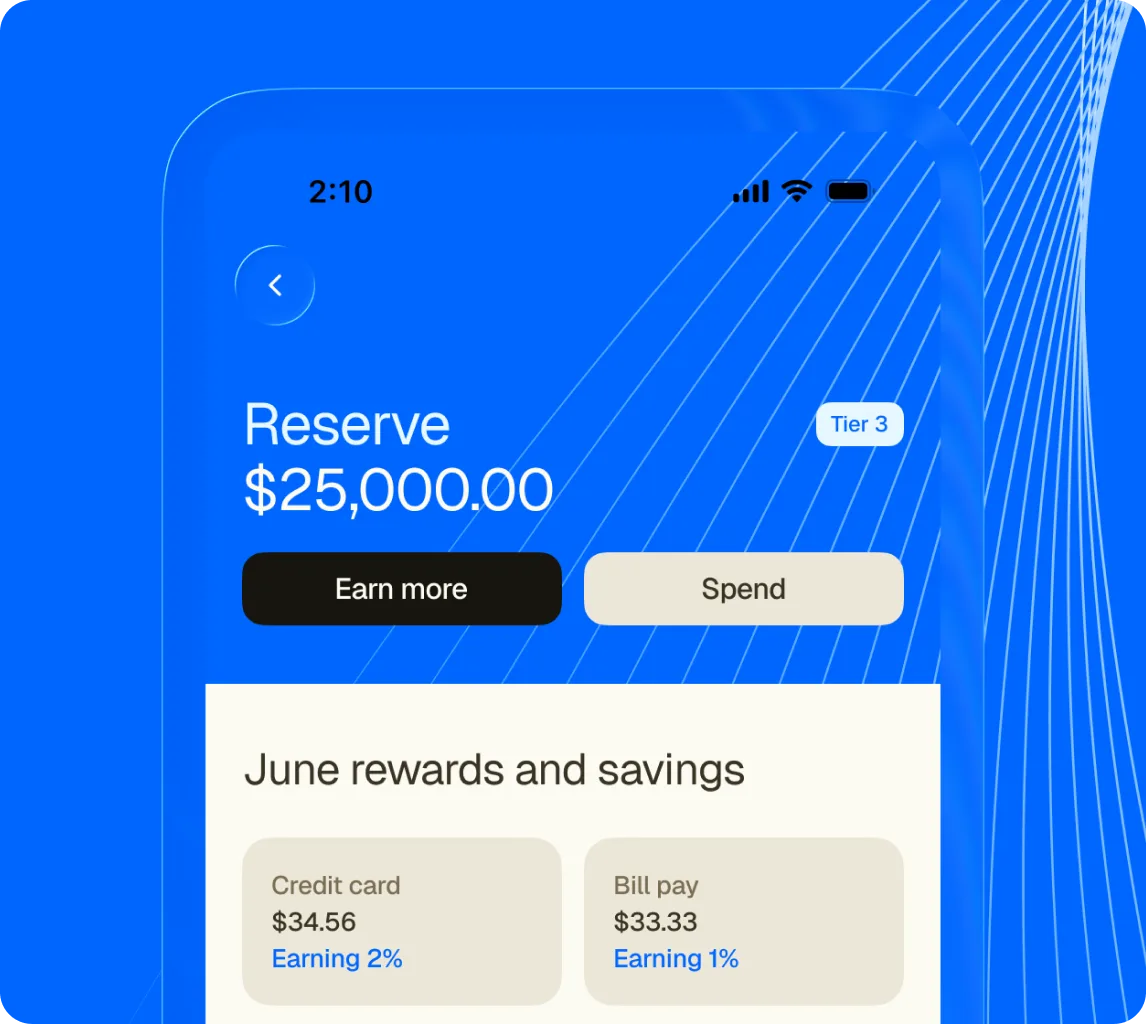
One balance. Three ways it pays.
Every action you already take, turned into rewards.
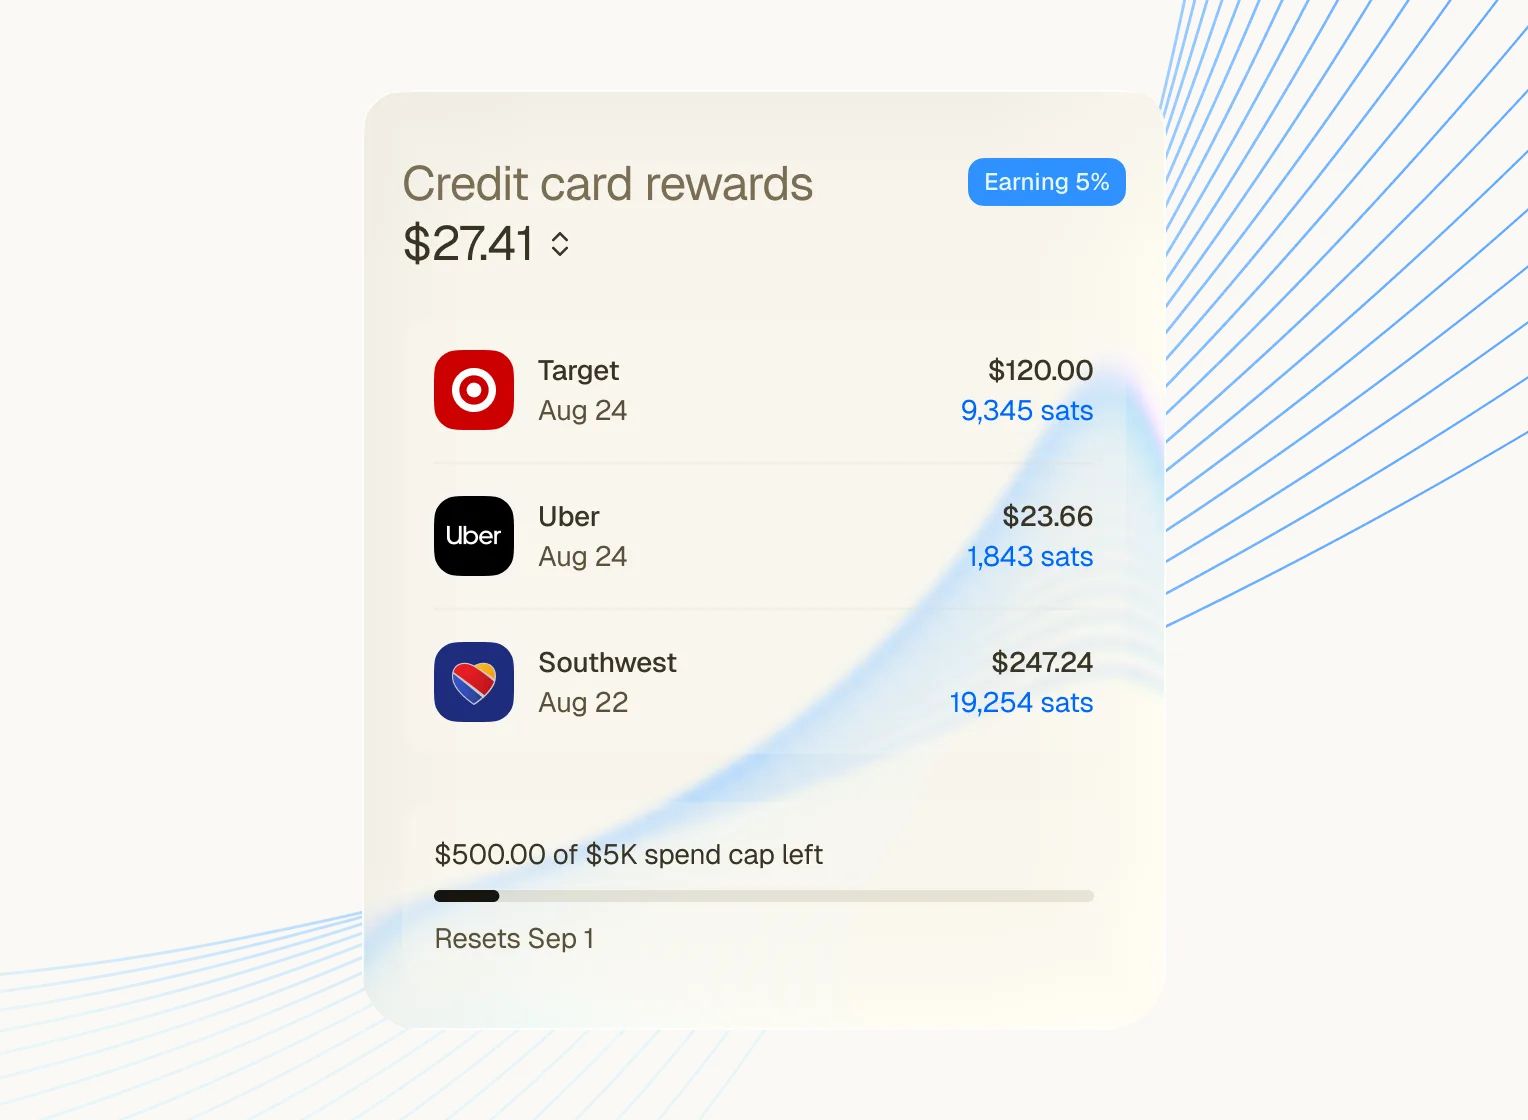
CREDIT CARD
Up to 5%* card rewards
Up to 5%* back on credit, up to 3% on debit, depending on your Reserve tier. Bitcoin back on every purchase, automatically.
* The 5% rate requires the Fold Bitcoin Credit Card and a $100,000 Fold Reserve balance, and applies to your first $5,000 in eligible purchases each month. 1.5% back in bitcoin on eligible purchases, with no cap. Rewards are earned on your eligible spend, not on your balance. Holding a Fold Reserve balance can boost your rate on your first $5,000 in eligible purchases each calendar month. Eligible purchases above that amount, and all eligible purchases if you do not hold a qualifying Reserve balance, earn the 1.5% base rate. Credit card and debit card rewards cannot be earned at the same time. Rates are subject to change. See the Cardholder Agreement and our Terms and Conditions.
BILL PAY
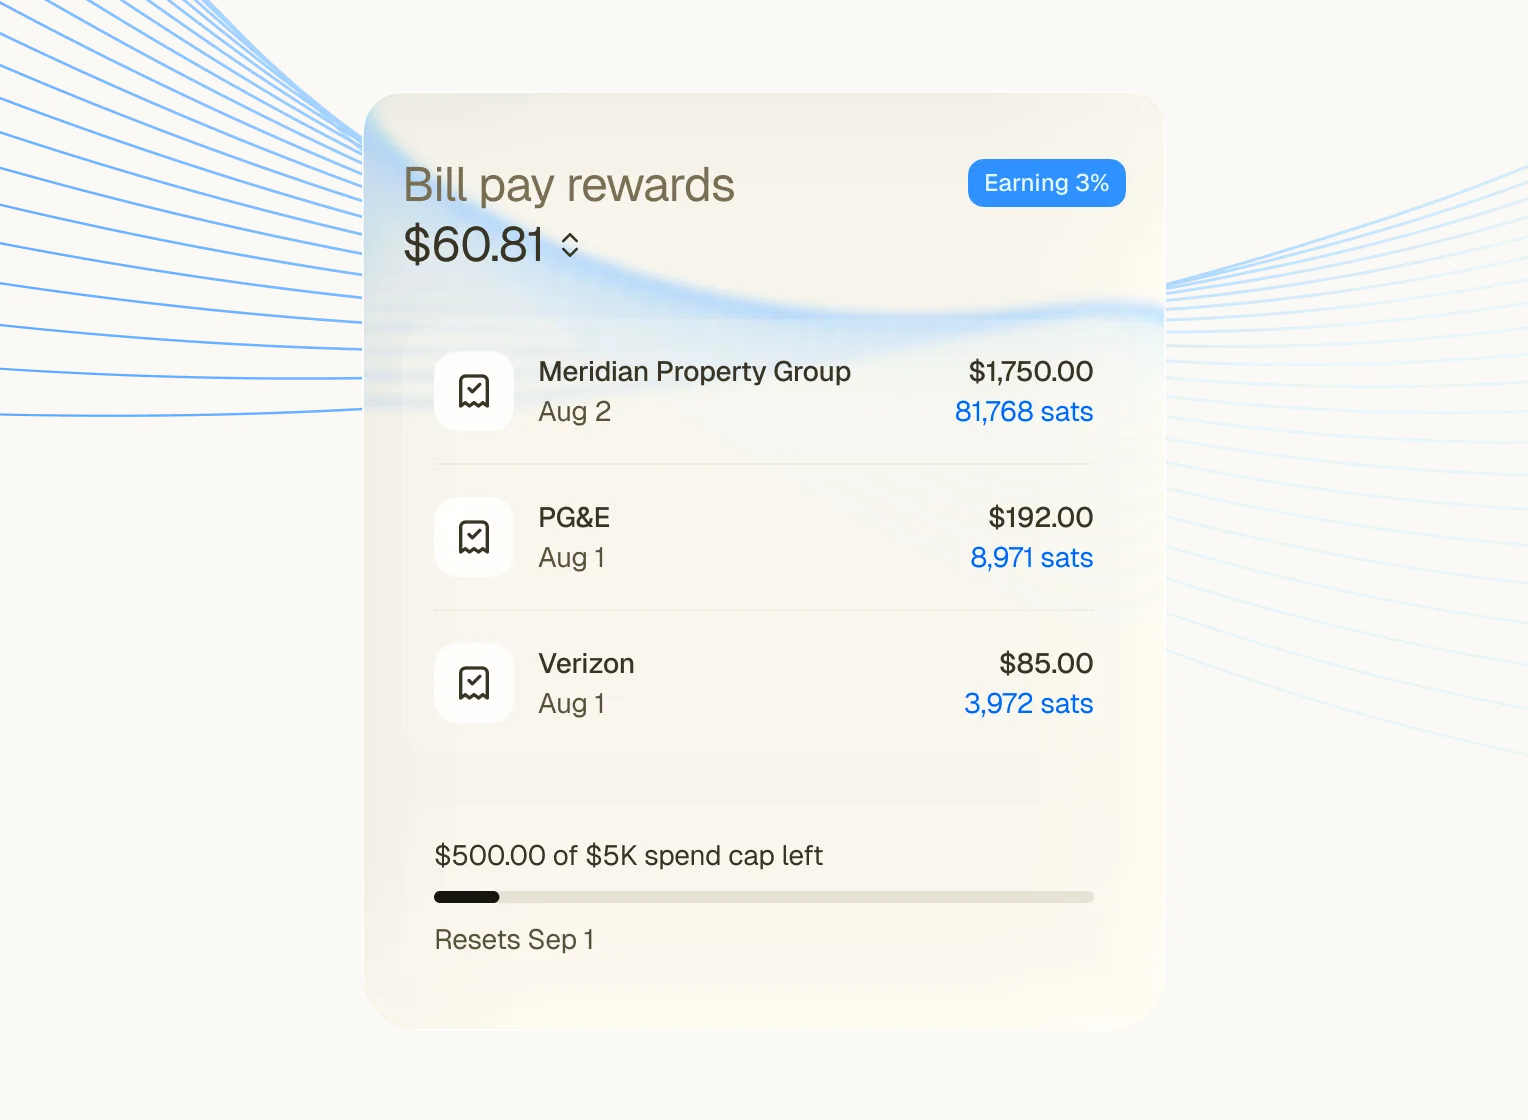
Up to 3% bill pay rewards
Rent, mortgage, utilities. The biggest bills you pay every month, finally earning something back.
EXCHANGE
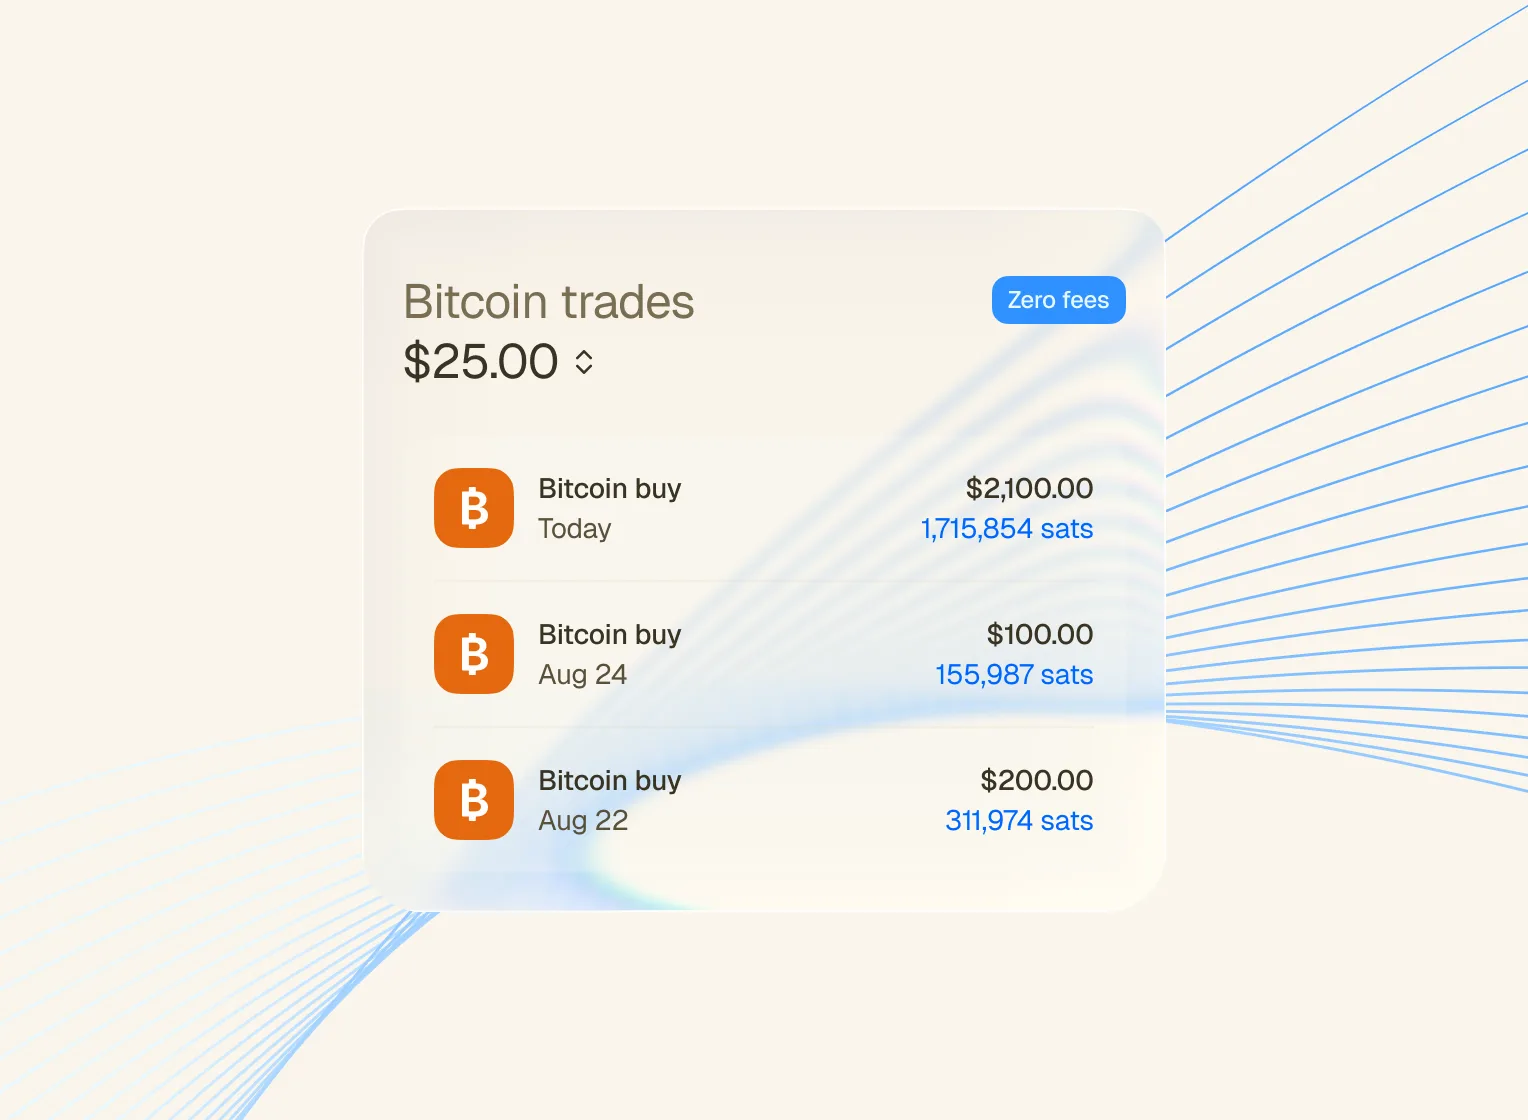
No transaction fee trades
Every exchange takes a cut before you even see the price. This one doesn't. Unlimited recurring buys, round-ups, one-time purchases — however you already stack.
WITHDRAWALS
Free on-chain withdrawals, included
Send bitcoin to your own wallet on us.
Pick a balance. See your rewards.
Pick a balance and enter what you spend each month. We'll show what you'd get back in bitcoin per year — assuming you use every monthly cap.
Reserve tier
Reserve tiers trade with no fee and no spread.
$1,750 more in bitcoin every year.
That’s a 7.0% annual return on your Reserve balance Return figures are rewards paid in bitcoin, not interest. Reserve is not an FDIC-insured deposit account. The 3% bonus is a limited-time offer that vests over three years, shown here as 1% of the balance per year; using the balance reduces the unvested bonus.
Credit card rewards
2% tier rate − 1.5% base = 0.5% on first $5K/mo
$300
Bill pay rewards
1% on first $5K/mo • 0% after
$600
Bitcoin trading
1% fee + spread avoided on all buys
$600
Commitment bonus
3% of $25,000 paid over 3 years = 1% per year
$250
Total added in bitcoin per year
$1,750
Claim your commitment bonus
Limited time 3% bonus, distributed over 3 years
Return figures are rewards paid in bitcoin, not interest. Reserve is not an FDIC-insured deposit account. The 3% bonus is a limited-time offer that vests over three years, shown here as 1% of the balance per year; using the balance reduces the unvested bonus.
Compare against the standard savings account
Same balance, one year. Savings interest is taxed as ordinary income, so the bank figures are shown net of a combined federal and state rate.
Fold Reserve
7.0% annual return
$1,750
High-yield savings
3.5% • 2.45% after tax
$613
Avg. savings
0.37% • 0.26% after tax
$65
How this comparison worksFold Reserve figures are rewards paid in bitcoin at the tier for the balance selected, assuming the card, bill-pay and bitcoin-buy amounts above are used in full every month, plus the limited-time 3% bonus spread evenly over its three-year vesting period. Rewards are not interest and are not guaranteed; tier rates, caps and the bonus can change. Bitcoin's dollar value changes after rewards are paid. Reserve is not an FDIC-insured deposit account and holds no interest-bearing balance.
BenchmarksThe high-yield savings APY defaults to 3.50%, below the top advertised online-savings rates (up to about 4.50% as of October 5, 2026) to reflect what a typical saver can hold over a year; the average savings APY defaults to the FDIC national average of 0.37% as of the same date. Both are variable rates that may have changed since, apply to the whole balance with no spending required, and are federally insured. Savings interest is shown net of an assumed 30% combined federal and state income-tax rate; your rate will differ.
LimitsThis is an illustration, not a forecast or an offer, and does not account for bitcoin price movements, tax on rewards, timing of bonus vesting, balance changes during the year or fees outside those listed. It is non-binding and provided for comparison only.
Here's how we compare
We believe your rewards should follow the way you spend. With Reserve they do.
Activate your Reserve Fold |  Coinbase1 |  Robinhood2 |  Chase3 |  Amex4 | |
|---|---|---|---|---|---|
| Total/yr | $6,300 | $2,350 | $1,750 | ~$1,020 | ~$895 |
| Credit* | Up to 5% | Up to 4% | 3% | 1.5% | 6% (capped) |
| Debit** | Up to 3% | 0.5%5 | 0% | 0% | ~0.5%6 |
| Bill pay | Up to 3% | 0% | 0% | 0% | 0% |
| Bonus | 3% | 0%7 | 0%7 | 0% | 0%7 |
* Credit rates are each provider's maximum published earn rate on eligible purchases; "up to" rates require the conditions noted. ** Debit rewards are shown as rates only and are not included in Total/yr.
1. Coinbase One Card: 4% requires $200,000 or more in Assets on Coinbase and applies to the first $10,000 in purchases per month (2% thereafter); customers with under $10,000 on Coinbase earn 2%. Requires a paid Coinbase One membership ($49.99/yr, deducted). Rewards paid in bitcoin. Total: 4% × $60,000 − $49.99.
2. Robinhood Gold Card: 3% on all purchases; requires an annual Robinhood Gold subscription ($50/yr, deducted) and a Robinhood brokerage account. 5% travel-portal rate not included. Total: 3% × $60,000 − $50.
3. Chase Freedom Unlimited: 1.5% on all purchases; 3% dining and drugstores and 5% Chase Travel not included; $0 annual fee. Total: 1.5% × $60,000.
4. American Express Blue Cash Preferred: 6% only at U.S. supermarkets (on up to $6,000/yr, then 1%) and select U.S. streaming; 3% transit and U.S. gas; 1% other. $95 annual fee after the first year (deducted). Total: 6% × $6,000 + 1% × $54,000 − $95.
5. Coinbase Card (Visa debit): Coinbase states the reward rate is variable and set in-app; 0.5% back (bitcoin, USDC, ether, or XLM) is the rate shown in the Coinbase app's Card rewards screen on September 25, 2026.
6. American Express Rewards Checking: 1 Membership Rewards point per $2 of eligible debit purchases, valued here at 1¢ per point; available to existing Amex customers only.
7. Card bonuses only. Yield paid on balances is excluded (Coinbase One 3.75% APY on USDC; Robinhood Gold 3.6% APY on cash; Amex Rewards Checking 1.00% APY).
Comparison disclosure
Timestamp and data recency
Competitor rates, fees, and program terms were reviewed on September 25, 2026 from each provider's public product and terms pages listed below. The most recent effective dates shown by the providers themselves were August 15, 2025 (Coinbase One Card Rewards Program Terms), September 17, 2026 (Robinhood Gold cash sweep rate), and September 24, 2026 (American Express Rewards Checking). The Coinbase Card debit rate was observed in the Coinbase app on September 25, 2026. Rates, fees, and program terms change frequently and may have changed since these dates. This comparison is reviewed quarterly and was last updated September 25, 2026.
Benchmark source and rate type
Reward rates shown are each provider's published headline earn rates on eligible card purchases, expressed as a percentage of net purchases. They are not annual percentage yields (APY) and are not interest on deposits. "Up to" rates are the maximum rate available under that provider's program and require conditions that many cardholders will not meet by default. Competitor rewards are paid in cash, points, or cryptocurrency according to each provider's terms; where rewards are paid in points, this comparison values them at 1 cent per point. Where rewards are paid in cryptocurrency, their U.S. dollar value fluctuates and may be worth more or less than the amount shown at the time of redemption. Competitor sources: Coinbase One Card Rewards Program Terms and product page and the Coinbase Card rewards help page; Robinhood Gold Card product page and Robinhood Gold support pages; Chase Freedom Unlimited product page; American Express Blue Cash Preferred and Rewards Checking product pages.
Comparison methodology and data limitations
Annual totals are estimates for a hypothetical customer who spends $60,000 per year on a credit card and who satisfies every condition required to earn each provider's maximum published rate. Totals are shown net of the membership or annual fees each program requires (Coinbase One $49.99 per year, Robinhood Gold $50 per year, American Express Blue Cash Preferred $95 per year after the first year; Chase Freedom Unlimited has no annual fee). Debit-card reward rates are shown for reference and are not included in annual totals. Actual rewards depend on your spending, merchant categories, account balances, subscription status, and each provider's caps and exclusions. In particular: the Coinbase One Card's 4% rate requires $200,000 or more in Assets on Coinbase (customers with under $10,000 earn 2%), applies to the first $10,000 in eligible purchases per calendar month (2% thereafter), and requires a paid Coinbase One membership; the Coinbase Card debit reward rate is variable and set by Coinbase, and the 0.5% shown is the rate displayed in the Coinbase app on September 25, 2026; the Robinhood Gold Card's 3% requires a paid Robinhood Gold subscription and a Robinhood brokerage account, and its 5% travel-portal rate is not reflected; Chase Freedom Unlimited earns 1.5% on all purchases, and its 3% dining and drugstore and 5% Chase Travel rates are not reflected; American Express Blue Cash Preferred earns 6% only at U.S. supermarkets (on up to $6,000 per year in purchases, then 1%) and on select U.S. streaming subscriptions, 3% on transit and at U.S. gas stations, and 1% on other eligible purchases; the American Express debit figure reflects 1 Membership Rewards point per $2 of eligible debit purchases on an American Express Rewards Checking account, valued at 1 cent per point, and is available only to existing American Express customers. Competitor totals exclude welcome bonuses, category and travel-portal bonuses, promotional offers, and any interest or yield paid on cash, stablecoin, or savings balances (for example, Coinbase One's 3.75% APY on USDC, Robinhood Gold's 3.6% APY on cash, and American Express's 1.00% APY on Rewards Checking). This comparison does not include every card or account offered by each provider and excludes providers not shown. Cash-back, points, and cryptocurrency rewards are not directly comparable.
No guarantee and non-binding notice
This comparison is for informational purposes only and is not an offer, a guarantee of rewards, or a statement of the terms of any account. It does not constitute investment, tax, legal, or financial advice. Actual rewards under any program are governed solely by that provider's cardholder agreement and rewards program terms, which the provider may modify, suspend, or terminate at any time. Competitor names, logos, and product information are the property of their respective owners, are used for identification and comparison only, and do not imply sponsorship, affiliation, or endorsement. Competitor information is taken from publicly available sources that Fold does not control, has not been verified with those providers, and may be incomplete or out of date; readers should confirm current terms directly with each provider before making any decision.
Competitor rates as of September 25, 2026, from each provider's public terms, based on $60,000/yr of credit-card purchases at each program's maximum rate, net of required membership and annual fees. "Up to" rates require asset minimums, spend caps, category limits, and paid memberships not shown; totals exclude debit rewards, welcome bonuses, and interest on deposits. Estimates only; not a guarantee of rewards and not an endorsement by any provider. See full comparison disclosure.
Sources (all opened September 25, 2026)
Coinbase: coinbase.com/creditcard · coinbase.com/legal/creditcard/rewards · help.coinbase.com (Coinbase Card rewards) · coinbase.com/one · in-app Card rewards screen. Robinhood: robinhood.com/creditcard · robinhood.com support: Gold overview, cash program interest rate, round-up rewards. Chase: creditcards.chase.com (Freedom Unlimited). American Express: americanexpress.com (Blue Cash Preferred; Rewards Checking).
Frequently asked questions
Fold Reserve is a new kind of balance, built for the money you're already moving through Fold. Swiping your card, paying a bill, buying bitcoin. Its only job is to make that activity as rewarding as possible.
Fund your Reserve and it does two jobs at once:
- It sets your rewards tier. The balance you commit sets your rates on card spend and bill pay. Higher tiers earn higher rates.
- It stays useful. Spend your Reserve on bitcoin, buy gift cards, or transfer to your Spending account on Fold.
Reserve is for people who already run a real share of their money through Fold, or want to. It's a good fit if you:
- Put regular spend on your Fold card
- Pay rent, your mortgage, or other bills through Fold
- Buy bitcoin regularly and would rather skip the Fold fee
- Keep a cash cushion somewhere anyway, and would rather it unlock better rewards
No, Fold is not a bank. Fold's banking services are provided by Lead Bank, Member FDIC.
Reserve is not FDIC insured. When you fund Reserve, you're purchasing prepaid value from Fold. It isn't a deposit, and the money isn't held in a separate account in your name.
Instead, Fold holds Reserve funds together in a pooled reserve, kept at Lead Bank and in U.S. Treasuries and money market funds. These funds fully back Reserve balances and are never lent out or rehypothecated.
Your Fold Spending balance works differently. That money is held at Lead Bank, Member FDIC, and is eligible for FDIC insurance up to applicable limits. You'll find it on the home screen of the Fold app.
You can use your Reserve anytime. There's no holding period, it doesn't expire, and there's no fee to hold it.
There are three ways to use it:
- Buy bitcoin. Use your Reserve to buy bitcoin on Fold. That bitcoin is yours.
- Buy gift cards. Use your Reserve to buy gift cards in Fold.
- Move to cash. Use your Reserve to buy bitcoin, then sell that bitcoin for dollars in your Fold checking balance. This transfer is instant and minimizes any potential slippage. From there you can pay bills, pay your credit card, use your debit card, or withdraw. Because this runs on bitcoin rails, a small amount of price movement between the buy and the sell is possible.
A few things to know:
- Reserve isn't a cash balance. That's why moving to cash happens through a bitcoin buy and a separate sell.
- Selling bitcoin can have tax consequences, even when the gain or loss is small.
- Using your Reserve lowers your balance. If it drops below your tier threshold, your rewards rate can drop too. Below $5,000, you lose Reserve tier benefits.
- All use is subject to the limits and controls in Fold's terms.
No, Reserve doesn't pay interest. Its benefits come from the money you move through Fold:
- No transaction fee and no added Fold spread on bitcoin buys
- Higher rewards on card spend and bill pay, earned in bitcoin
That trade works on money that's moving, not money that's sitting.
It's important to know that while a savings account pays interest, the bank keeps a cut of what your money earns first, and the interest you get is taxed as income. Fold doesn't take a cut, and rewards on spending aren't taxed.
How much you put in Reserve is up to you. Use the calculator to estimate your rewards based on how much bitcoin you buy, your monthly bills, and what you spend on your Fold card.
Boosted rewards apply to the first $5,000 in card spend and the first $5,000 in bill pay each month. After that, rewards return to your base rate until the 1st of the next month. Boosted card rewards apply to one card: your Fold credit card if you have one, otherwise your Fold debit card.
Your tier is set by the amount of Reserve you hold and determines your rewards rate. Using your Reserve to buy bitcoin or gift cards can move you to a lower tier. Rates and tier thresholds are set out in the Fold Reserve Terms and Conditions and may change upon notice. Tier 1, $5k, gets you fee-free bitcoin and bill-pay rewards.
| Tier | Reserve | Credit card | Debit card | Bill pay | Bitcoin trading | Withdrawals |
|---|---|---|---|---|---|---|
| Non-Reserve | $0–$4,999 | 1.5% | 0.25% | 0% | 1% fee + spread | Network fee |
| 1 | $5,000 | 1.5% | 0.25% | 0.25% | 0% fee + 0% Fold spread | Free |
| 2 | $15,000 | 1.75% | 0.5% | 0.5% | 0% fee + 0% Fold spread | Free |
| 3 | $25,000 | 2% | 1% | 1% | 0% fee + 0% Fold spread | Free |
| 4 | $50,000 | 3% | 1.5% | 1.5% | 0% fee + 0% Fold spread | Free |
| 5 | $75,000 | 4% | 2% | 2% | 0% fee + 0% Fold spread | Free |
| 6 | $100,000 | 5% | 3% | 3% | 0% fee + 0% Fold spread | Free |
You will earn the tiered reward rate on the first $5,000 in spending via the Fold Bitcoin Credit Card by default, or the Fold Prepaid Debit Card if you do not have or do not use a Fold Bitcoin Credit Card. Spending above $5,000 earns 1.5% on credit, 0.25% on debit, and nothing on bill pay.
Fund your Reserve during the launch window and you can earn a bonus worth 3% of your balance. You'll see the full amount in your membership value right away, but it pays out in three parts, one a year, in bitcoin. Your Reserve has to have stayed funded when each payout comes due. Most bonuses reward spending. This one rewards leaving your money alone.
Everything your money should be doing.
Spend, save, give, and grow. All while earning bitcoin.
- Visa-backed
- Bitcoin secured by BitGo
- Available in the U.S.
Start earning bitcoin on what you already spend.
Download the Fold app, set up your account, and use your card like normal. Your bitcoin balance takes care of itself.